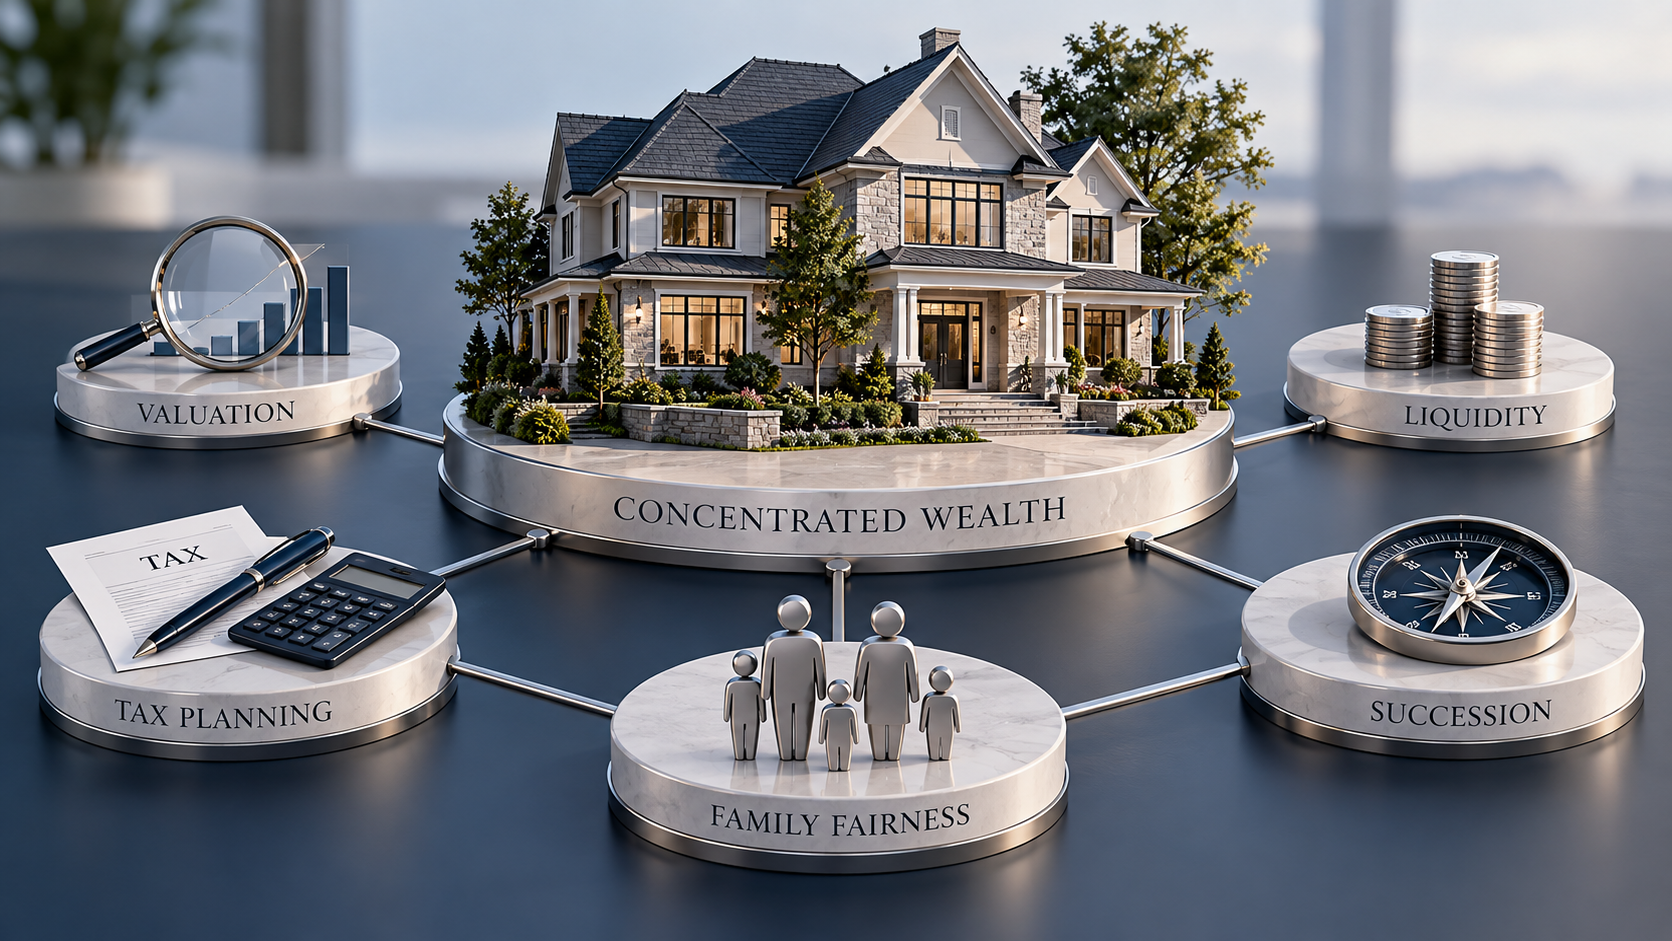
A family can have substantial wealth without having much flexibility.
For a business founder, most of the family’s net worth may be tied to one closely held company. A real estate investor may own a valuable commercial property that represents the majority of the estate. An executive may have accumulated a large position in one company’s stock.
On a personal balance sheet, each family may appear financially secure. But from an estate planning perspective, having most wealth concentrated in a single asset can create difficult questions.
How will the asset be valued? Where will cash come from to pay taxes and estate expenses? Can the asset be divided among beneficiaries? What happens if some beneficiaries want to keep it and others want cash? What if its value changes dramatically before the estate plan is implemented?
Effective estate planning for concentrated wealth requires looking beyond the total value of the estate and considering what the wealth actually consists of.
A $10 Million Estate May Not Function Like a $10 Million Estate
Consider two families, each with a net worth of $10 million.
The first owns a diversified mix of marketable investments, cash, retirement accounts, and other assets. The second owns a business worth approximately $8 million and has $2 million in other assets.
The totals are the same. The planning challenges are not.
The first family may have several sources of liquidity and considerable flexibility when dividing assets among beneficiaries. The second family’s ability to accomplish the same objectives depends heavily on one business.
That business cannot necessarily be divided into convenient pieces without affecting control. It may be difficult to sell. Its appraised value may not equal what a buyer would actually pay. And extracting cash from it to satisfy estate obligations could weaken the company itself.
Similar problems arise when the concentrated asset is a large real estate holding or investment position.
This is why fundamental estate planning should consider not only net worth, but the character, ownership, liquidity, and concentration of the assets making up that net worth.
Valuation Becomes Especially Important
When one asset represents most of an estate, its valuation can affect almost every other planning decision.
A publicly traded investment has an observable market price, although that price may fluctuate significantly. Closely held businesses and private real estate are different. Their values may depend on appraisals, financial performance, market conditions, ownership restrictions, discounts, debt, and other factors.
Suppose a parent plans to leave a business to one child and other assets of approximately equal value to two other children. If the business is assumed to be worth $6 million when the plan is created, the division may appear reasonable.
Ten years later, the company could be worth $12 million—or $3 million.
Unless the plan is reviewed, an allocation intended to treat the children comparably may produce a very different result.
Valuation is therefore not simply an issue that arises after death. It can be central to designing and maintaining the plan during life.
Equal on Paper Does Not Always Mean Economically Equal
Concentrated estates can also make the concept of equal inheritance more complicated.
Imagine two children. One receives a $5 million interest in a family company, while the other receives $5 million in marketable investments.
Those inheritances have the same stated value, but they are not economically identical.
The investment portfolio may be readily sold and diversified. The business interest may be illiquid and subject to operating risk. It may produce substantial future income and appreciation—or decline in value. It may also require the beneficiary to remain actively involved in the company.
The same problem can occur with real estate. A beneficiary who receives a valuable apartment building has received both an asset and the responsibilities associated with owning it. Another beneficiary receiving liquid investments has far greater flexibility.
None of this means concentrated assets should not be used to divide an estate. It means fairness should be evaluated more thoughtfully than simply comparing appraised values on a particular date.
Liquidity Can Become a Problem at Exactly the Wrong Time
A concentrated estate may be wealthy but cash-poor.
After a death, the estate may need funds for taxes, debts, administration expenses, professional fees, property expenses, or distributions to beneficiaries. If most wealth is tied to one asset, generating that cash may be difficult.
A family should not assume that a valuable asset can simply be sold when cash is needed.
A closely held company may require months or years to prepare for sale. A commercial property may encounter unfavorable market conditions. A large investment position may have tax or market consequences if it must be liquidated quickly.
The result can be a forced sale at a time chosen by circumstances rather than by the family.
Planning may therefore include cash reserves, life insurance, borrowing capacity, income-producing assets, or other sources of liquidity. For estates potentially subject to estate tax, those decisions should also be coordinated with estate tax planning.
The objective is not necessarily to create enough cash to eliminate every possible problem. It is to avoid discovering after a death that the only practical way to meet estate obligations is to dispose of the family’s most important asset.
Different Assets May Be Appropriate for Different Beneficiaries
Concentrated wealth also raises an important question: Does every beneficiary need to inherit part of the concentrated asset?
Sometimes the answer is no.
If one child operates a family business and another has no involvement, dividing the company equally may create management and governance problems. If one beneficiary has managed a family real estate portfolio for years while another wants no responsibility for it, fractional ownership may serve neither person well.
The estate plan may instead allocate the concentrated asset primarily to the beneficiary best positioned to own or manage it and use other assets, life insurance, trusts, or buyout arrangements to provide value to other beneficiaries.
This approach overlaps with business succession planning when the concentrated asset is a closely held company. The central issue, however, applies beyond businesses: ownership should be structured according to the characteristics of the asset and the circumstances of the beneficiaries, not merely divided by headcount.
Trusts and Entities Can Provide Structure
Trusts, LLCs, partnerships, and other entities may provide useful structures for concentrated assets.
A trust can establish who benefits from an asset, who controls it, when distributions may be made, and how the asset should eventually pass to future generations. An entity can provide rules governing management, voting, transfers, buyouts, and ownership among multiple family members.
These structures may be particularly useful when the family wants to preserve an asset without giving every beneficiary identical control.
They can also create their own complexities. The trust and entity documents must work together. Beneficiaries need to understand their rights. Managers or trustees need sufficient authority to make decisions. And there should be a realistic process for dealing with a beneficiary who eventually wants liquidity.
For families with significant concentrated wealth, these issues may form part of broader advanced planning strategies involving tax planning, asset protection, wealth transfer, and family governance.
Plan for the Beneficiary Who Wants Cash
A plan built around preserving a concentrated asset should still contemplate the possibility that a beneficiary may not want to own it.
A child who inherits an interest in a private company may prefer a diversified investment portfolio. A beneficiary of family real estate may live across the country and have no interest in property management. Another may simply need cash.
Buyout provisions can establish how an ownership interest will be valued, who has the right to purchase it, and how the purchase price will be paid.
Installment payments may sometimes make a buyout more feasible when the asset itself does not generate enough cash for an immediate purchase. In other situations, insurance or other liquid assets may provide the resources needed to equalize inheritances without forcing a sale.
The important point is to anticipate the disagreement before it happens.
Concentrated Investment Positions Present Their Own Challenges
Not every concentrated estate involves a business or property.
Executives and longtime investors may hold a significant percentage of their wealth in one publicly traded company. The asset is technically liquid, but that does not eliminate planning concerns.
A large position can fluctuate sharply in value. Selling it may have significant tax consequences. The owner may have emotional attachment to the investment or restrictions affecting when shares can be sold.
Estate planning should not automatically become investment advice. Whether an individual should retain, diversify, hedge, or sell a concentrated position depends on financial, tax, investment, and personal considerations that extend beyond the estate plan.
But the estate plan should recognize the concentration rather than assuming the asset will always have today’s value or can be divided without consequence.
A Plan Based on Today’s Values Needs to Be Reviewed
Concentrated wealth can change an estate plan faster than diversified wealth.
A business may experience rapid growth. A major property may appreciate substantially. A stock position may double—or lose a significant portion of its value.
Suppose an estate plan leaves a business to one child and $4 million of other assets to another because the business is also worth approximately $4 million.
Years later, the business is worth $10 million while the other assets remain close to $4 million.
The documents may still work exactly as drafted. The economic result, however, may no longer resemble what the parent intended.
Regular review is therefore particularly important when a substantial percentage of family wealth is concentrated in one asset. Changes in value, ownership, debt, family circumstances, tax law, or the owner’s objectives may all require adjustments.
Plan Around the Assets You Actually Own
Estate planning for concentrated wealth begins with a simple recognition: net worth alone does not tell the whole story.
A business, commercial property, family real estate holding, or concentrated investment position may create substantial wealth while also limiting liquidity and flexibility. The estate plan needs to account for both realities.
That means considering valuation, taxes, liquidity, control, beneficiary circumstances, buyouts, future appreciation, and the possibility that an asset may eventually need to be sold.
The objective is not necessarily to diversify the asset or preserve it forever. It is to create a plan capable of working even when most of the family’s wealth cannot simply be divided into equal checks.
Miller Legal Group helps business owners, investors, and families coordinate concentrated assets with estate, trust, tax, and wealth-transfer planning. If a significant portion of your family’s net worth is tied to one business, property, or investment, contact Miller Legal Group to review whether your estate plan has sufficient flexibility for valuation changes, liquidity needs, taxes, and the interests of different beneficiaries.